Moneta Funded Expected Value and Every Plan Compared | Buy the 2-Step. The New 1-Step Is Overpriced, and Instant Pro Is Only a Fair Trade Even at Half Price [November 2026]
※ Rules were confirmed on Moneta Funded's official site and official help center on September 27, 2026. The 1-Step rebuild, 1-Step Daily, EA rules, refunds, and coupons were confirmed on October 12, 2026. Each price table states the date it was checked (some prices seen at checkout in September differ from the September 27 list prices). Check the final checkout screen before you buy.
※ On November 7, 2026, we merged four articles into this one: "Moneta Funded instant account guide," "Is the half-price coupon for Moneta Instant Pro worth it?", "Instant or two-phase: which should you buy?", and "Moneta 2-Step: 4%/8% or 5%/10%?"
Conclusion
- If you're buying now, the default is the 2-Step. At 1% risk per trade, among the plans you can buy today, 2-Step 5%/10% ranks #1 with +$22,016 for the year (medium skill), followed by 4%/8% at +$20,234.
- The 1-Step was rebuilt in October 2026 and is now overpriced. The new 1-Step costs $1,098 for $100K, has a 5% trailing max loss, and fails instantly when floating loss on one symbol reaches 1%. You pay $220 per $1,000 of loss room, about 2.6x the 2-Step ($83–$86). Because of the 1% floating-loss rule you can't risk 1% per trade, so we haven't calculated its expected value. The 1-Step column in the EV tables below is for accounts bought before the change (6% static, $780).
- For the two 2-Step configurations: 5%/10% if you're betting on one account, 4%/8% if you're buying many. 5%/10% cuts the fail rate by up to 12.6 points and has the higher expected value per account at every skill level. 4%/8% is more efficient per dollar at every skill level. If you hold overnight or stack positions on one symbol, that's another reason to pick 5%/10%.
- Instant (20% consistency, 88% split) only works at 0.5% risk per trade. On Instant accounts bought on or after September 21, 2026, the account fails instantly when floating loss on one symbol reaches 1% of the account. At 0.5% it ranks #1 of all plans (+$17,017 at medium skill), but the 2-Step 5%/10% at 1% (+$22,016) is higher.
- Instant Pro is close to worthless if you're buying for expected value. The most a zero-edge trader should pay is 2.755% of the account. The $5,300 list price (5.300%) is about twice its value (0.52x). At 50% off ($2,650) it's a 1.04x fair trade, and with a cost of 0.01% per trade it drops to 0.82x. It also ranked last under every condition in the 1-year simulation. Half price doesn't make it a bargain; it just brings an overpriced product back to fair value.
- As of October 12, the coupon on the official banner is
monetober40(40% off). Every figure in this article that assumesTOKONATSU50(50% off) uses prices where we confirmed the code at checkout on September 10–12. We haven't checked whetherTOKONATSU50still works after October. - Self-built EAs are allowed even when fully automated (support confirmed this in writing for the 2-Step on October 12, 2026). Commercial EAs and martingale/grid types are not.
Specs for every plan ($100K)
Evaluation plans (1-Step, 2-Step)
| 2-Step 5%/10% | 2-Step 4%/8% | 1-Step (new, from Oct 2026) | 1-Step (accounts bought before the change) | 1-Step Daily (new) | |
|---|---|---|---|---|---|
| Price (list) | $855 | $660 | $1,098 | $780 | $284 |
| Target | 5%→10% | 5%→10% | 10% | 10% | 3% |
| Daily loss | 5% | 4% | 3% | 3% | 1% |
| Max loss | 10% (static) | 8% (static) | 5% trailing (locks at starting balance; also locks when a payout is approved) | 6% (static) | 2% (static; fixed at starting balance when a payout is approved) |
| Floating loss on one symbol | Closed out at 3% on funded | Closed out at 2% on funded | Instant fail at 1% | Closed out at 2% on funded | - |
| Minimum days | 3 days with 0.5%+ profit (each phase) | Same | 3 days with 0.5%+ profit after funding | 3 days with 0.5%+ profit | - |
| Consistency | None | None | None | None | - |
| Payouts | Every 14 days, $100 minimum | Same | Every 14 days | Every 14 days | Daily ($2,000 cap per payout) |
| Fee refund | In full on the 4th payout | Same | Same | Same | Same |
| Leverage (FX) | 1:100 | 1:100 | 1:30 | 1:30 | 1:30 |
Price dates: the 2-Step, the new 1-Step, and 1-Step Daily were checked October 12; the old 1-Step is the September 27 list price. The 2-Step 5%/10% was $950 when we checked the checkout on September 12 (the "Prices for every size" table and part of the simulations below use that price).
1-Step accounts bought before the change keep the old rules (6% static, floating loss allowed up to the max loss). The official help center says purchases made before the change stay on the previous rules. The 2-Step, Instant, and Instant Pro did not change in October, in rules or price.
The 2-Step profit target is 5% in Phase 1 and 10% in Phase 2. That's the reverse of the usual industry setup; two-thirds of the combined 15% sits in Phase 2.
Instant plans (no evaluation)
| Instant (20%/88%) | Instant Pro | Phoenix Instant | |
|---|---|---|---|
| Price ($100K list) | $877 | $5,300 | $80K $4,299 (cut in October) |
| Daily loss | 3% | 4% | 3% |
| Max loss | 5% trailing (locks at starting balance) | 8% trailing (locks at starting balance) | 6% (static) |
| Max loss after a payout | Rises to the starting balance when a payout is approved | Rises to the starting balance when a payout is approved | - |
| Consistency | One day's profit capped at 20% of total profit (15% also available) | None | None |
| Profit split | 88% (60% also available) | 88% | 88% |
| Daily profit cap | None | 4% (auto-close and paused until the next day) | None |
| Floating loss on one symbol | Instant fail at 1% (accounts bought on/after Sep 21, 2026) | Close-out rule (see below) | - |
| News trading | Not allowed | Allowed | Allowed |
| Minimum profit days | None | None | 3 days (0.5%+ each) |
| First payout | 14 days after first trade | Any time (from $100) | 14 days |
| Fee refund | None | None | None |
| Leverage (FX) | 1:30 | 1:30 | 1:30 |
Instant prices are September 27 list prices. When we checked the checkout on September 9, Instant 20%/88% at $100K was $1,450 (all sizes in the table below).
Rules that apply to every plan
- Daily loss is "today's reference − starting balance × daily %." The reference is the higher of balance and equity at 22:00 UTC (7:00 JST) each day. Breaches are judged on equity (floating loss included).
- "Trailing" max loss follows the account's high (the higher of balance and equity, including the highest floating profit) at 5% (Instant) or 8% (Instant Pro) below. Once the line rises to the starting balance, it stops there. On Instant and Instant Pro accounts bought on or after September 21, 2026, the line moves up to the starting balance as soon as a payout is approved.
- The floating-loss-per-symbol rule (funded accounts other than Instant): when that symbol's floating loss hits the threshold, all positions are closed and trading stops for the day; after that, risk is capped at 1.5% of the account per trade. Lifting the cap takes 14 days plus 20 trades on another funded account. For Instant Pro, the same help article states the threshold as both 3% and 2%, and we couldn't confirm which is correct. We found nothing in the help center saying the same trigger applies during evaluation.
- News: no opening, closing, or TP/SL fills within 5 minutes before or after ForexFactory red-folder events (all symbols tied to USD, EUR, GBP, JPY, AUD, CAD, CHF, NZD, CNY). Positions opened 2+ hours before the event may close or hit TP/SL inside the window. Instant Pro and Phoenix Instant allow news trading.
- 30 days with no trading = fail. No time limit; weekend holding is allowed.
- Leverage (1:30 plans): FX 1:30, metals 1:10, indices 1:8, oil 1:3, crypto 1:1.
- Platforms: MT5 / Match-Trader (no cTrader, TradeLocker, DXtrade, or MT4).
- Commission: FX and metals $4/lot round turn; indices, energy, and crypto free.
- Limits: Instant up to $100K×1 or $50K×2 (no mixing sizes). Instant Pro has a separate $100K allowance.
Prices for every size
Evaluation plans
| Account size | 2-Step 4%/8% | 2-Step 5%/10% | New 1-Step | Old 1-Step | 1-Step Daily |
|---|---|---|---|---|---|
| $5K | $33 | $45 | $69 | $42 | - |
| $10K | $71 | $105 | $137 | $90 | - |
| $25K | $169 | $245 | $295 | $215 | - |
| $50K | $365 | $526 | $549 | $465 | $142 |
| $100K | $660 | $950 | $1,098 | $840 | $284 |
| $200K | - | - | $1,998 | - | - |
The 2-Step was measured at checkout on September 12, 2026 and the old 1-Step on September 13. The new 1-Step and 1-Step Daily were checked on October 12. 1-Step Daily caps each payout at $1,000 ($50K) / $2,000 ($100K).
The price gap between the two 2-Step configurations is about 1.4x at every size ($5K 1.36x, $10K 1.48x, $25K 1.45x, $50K and $100K 1.44x).
Instant plans
| Account size | Instant 15%/60% | Instant 20%/88% | Other combinations | Instant Pro |
|---|---|---|---|---|
| $5K | $40 | $69 | 15%/88% $55, 20%/60% $49 | $250 |
| $10K | $80 | $155 | 15%/88% $120, 20%/60% $105 | $500 |
| $25K | $195 | $369 | 15%/88% $280 | $1,250 |
| $50K | $415 | $799 | 15%/88% $605 | $2,400 |
| $100K | $750 | $1,450 | 15%/88% $1,099 | $5,300 |
List prices confirmed at checkout on September 9, 2026 (MT5 selected; Match-Trader was the same). On September 27, the $100K list price was $877 for Instant 20%/88% and $454 for 15%/60%.
The 88% split is a paid option. At $10K, the gap between 60% and 88% is $75. The difference in what you receive is 0.28P on profit P, so with the $38 gap after 50% off, 88% pays for itself at $136 of profit. Don't pick the 60% split.
Phoenix Instant list prices in September were $2.5K $195 / $5K $350 / $10K $600 / $20K $1,150 / $40K $2,600 / $80K $5,400, cut in October to $2.5K $155 / $10K $479 / $80K $4,299. The account grows every 10% (up to $2M), so it's for people who want scaling.
Coupons
| Code | Discount | Source | Status |
|---|---|---|---|
monetober40 | 40% off | Official site banner | Shown as of October 12 (no end date stated) |
TOKONATSU50 | 50% off (labeled for first purchase by the distributor) | Moneta Funded's Japan business developer Natsuki Nuts, in the note post "All 6 plans explained" (September 8) | Confirmed on Instant / Instant Pro / 1-Step / 2-Step / Phoenix on September 10–12. Not checked after October |
TOKONATSU | 42% off (standing) | Same note post | $80 → $46 confirmed on September 10 |
BACK2TRADE | 30% off | Official banner (September) | Confirmed on September 10 |
FLASH40 | 40% off | Official banner | Ended at the end of September |
- Codes can't be combined. There's one promo field; the code you enter last replaces the earlier one.
- Changing size, configuration, consistency, or split clears the code. Set the configuration first, enter the code last, check the total, then click Continue. The
?coupon=URL in the note post did not auto-fill the promo field. - We tested
TOKONATSU50at checkout while logged out, so we couldn't confirm whether its "first purchase" condition blocks a second purchase. The distributor intendsTOKONATSU(42%) for later purchases.
Prices with 50% off (TOKONATSU50, September 10–12, 2026)
Bold = measured; others are half the list price (rounded .5 up). List price at the time in parentheses.
| Plan | $5K | $10K | $25K | $50K | $100K |
|---|---|---|---|---|---|
| Instant 20% consistency / 88% | $35 ($69) | $78 ($155) | $185 ($369) | $400 ($799) | $725 ($1,450) |
| Instant 15% consistency / 88% | $28 ($55) | $60 ($120) | $140 ($280) | $303 ($605) | $550 ($1,099) |
| Instant 15% consistency / 60% | $20 ($40) | $40 ($80) | $98 ($195) | $208 ($415) | $375 ($750) |
| 1-Step (before the change) | $21 ($42) | $45 ($90) | $108 ($215) | $233 ($465) | $420 ($840) |
| 2-Step 5%/10% | $23 ($45) | $53 ($105) | $123 ($245) | $263 ($526) | $475 ($950) |
| 2-Step 4%/8% | - | - | - | - | $330 ($660) |
| Instant Pro | $125 ($250) | $250 ($500) | $625 ($1,250) | $1,200 ($2,400) | $2,650 ($5,300) |
Phoenix $10K at 50% off measured $300 (September list price $600).
Every figure in this article that assumes TOKONATSU50 (Instant Pro's maximum price and multiples, the Blueberry comparison, the net value and multiples in the 2-Step configuration comparison, and the Fintokei comparison) uses the 50%-off prices above. If 50% isn't available and you use monetober40 (40% off), Instant Pro $100K costs $3,180 and the multiples fall further.
The new 1-Step and 1-Step Daily (October 2026)
Take a $100K 1-Step. Before the change, you didn't fail until you'd lost $6,000. Now the account ends the moment any one trade's floating loss reaches $1,000. The max loss is also $5,000 and rises with your profits.
| Plan ($100K) | Max loss room | Price | Per $1,000 of room |
|---|---|---|---|
| 1-Step (new) | $5,000 (trailing) | $1,098 | $220 |
| 2-Step 4%/8% | $8,000 (static) | $660 | $83 |
| 2-Step 5%/10% | $10,000 (static) | $855 | $86 |
The new 1-Step costs about 2.6x the 2-Step per unit of room, and the room shrinks because it trails. On top of that, the 1% floating-loss rule means each trade must risk less than 1% to the stop. Because losses stop at the fee, sizing up to the rule limit is the basic way to raise expected value at a prop firm, and the new 1-Step caps that limit at 1%. The comparison page doesn't show expected value for it either.
1-Step Daily is cheap ($284 for $100K) and pays out daily. But with a 1% daily loss and 2% max loss, the room is very tight, and your size has to shrink to match. It's for people who stack one trade a day with roughly a 0.5% stop.
2-Step: 4%/8% or 5%/10%?
The two configurations differ in only three things: daily loss (4% / 5%), max loss (8% / 10%, both static), and the floating-loss-per-symbol trigger (2% / 3%). Targets, minimum days, time limit, leverage, split, payouts, and refund are the same.
The difference that matters most: target ÷ max loss
| 4%/8% | 5%/10% | |
|---|---|---|
| Phase 1: target ÷ max loss | 5% ÷ 8% = 0.63 | 5% ÷ 10% = 0.50 |
| Phase 2: target ÷ max loss | 10% ÷ 8% = 1.25 | 10% ÷ 10% = 1.00 |
4%/8% Phase 2 asks you to make 10% when you can only lose 8%. With 5%/10%, target and loss room are exactly 1:1. The 44% price gap isn't really buying "2 more points of drawdown"; it's buying enough room for the target. Phase 1's target is smaller than the room in both, so Phase 2 is where people get stuck.
Fail rates (40,000-run Monte Carlo)
One trade = +R×r with win rate p, −r on a loss. 3 trades a day, 1% per trade, 120 business days, 40,000 runs. Fees are the September 12 checkout prices with TOKONATSU50 applied: $330 (4%/8%) and $475 (5%/10%).
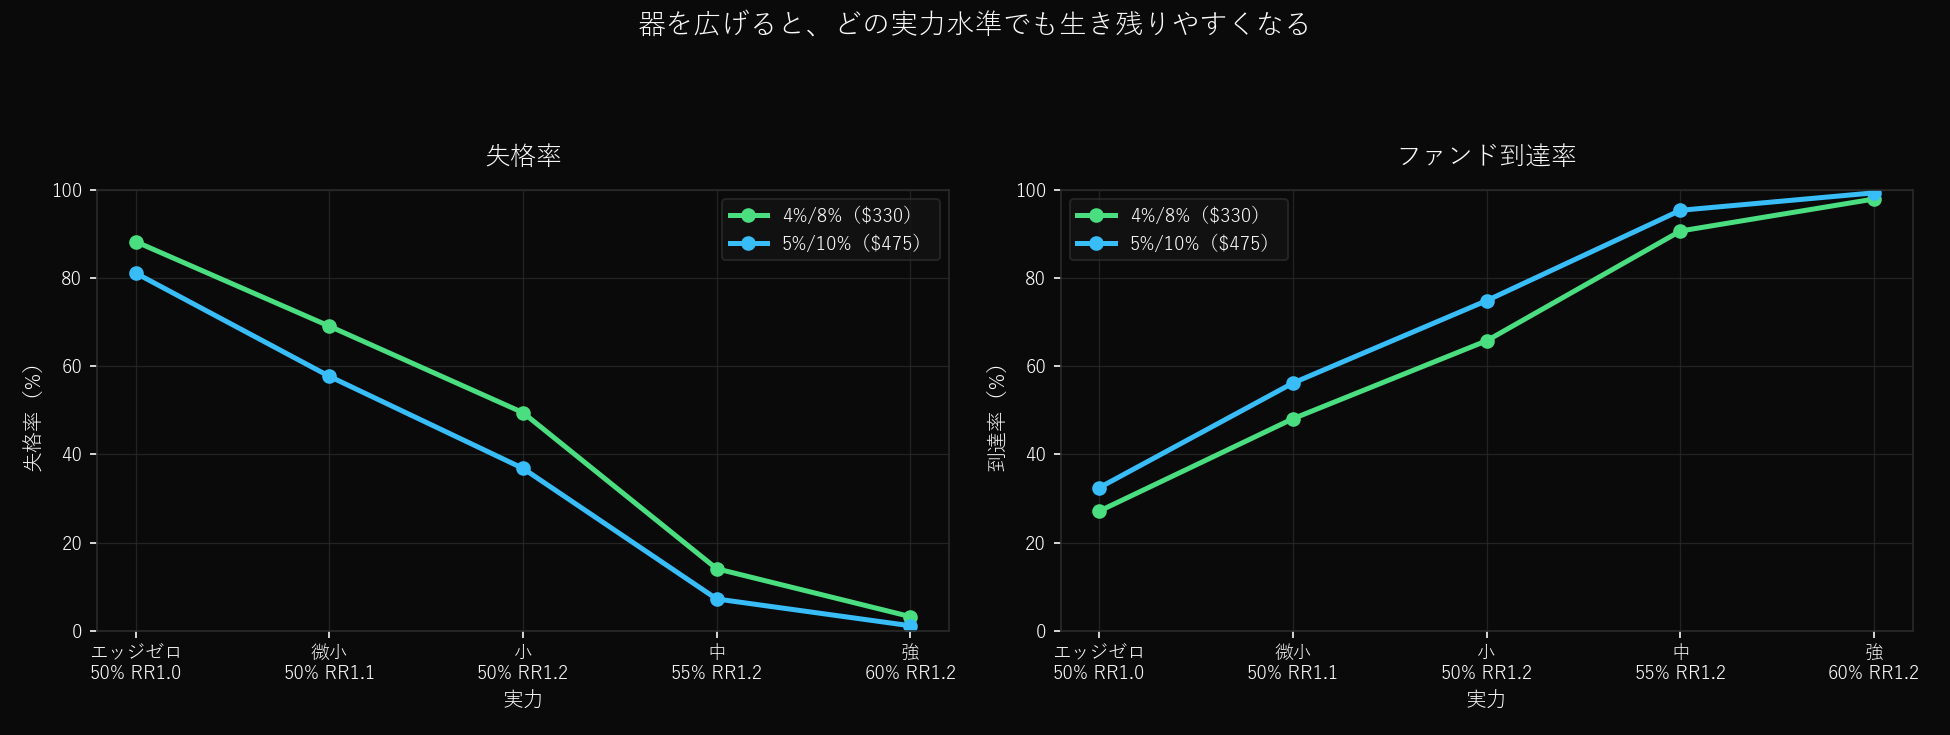
| Skill (60-day equivalent) | 4%/8% fail rate | 5%/10% fail rate | Diff | 4%/8% reach funded | 5%/10% reach funded |
|---|---|---|---|---|---|
| Zero edge (50%, RR1.0) | 88.2% | 81.1% | −7.1pt | 27.1% | 32.4% |
| Tiny (50%, RR1.1) | 69.1% | 57.7% | −11.4pt | 48.1% | 56.2% |
| Small (50%, RR1.2) | 49.4% | 36.8% | −12.6pt | 65.8% | 74.9% |
| Medium (55%, RR1.2) | 14.1% | 7.2% | −6.9pt | 90.6% | 95.3% |
| Strong (60%, RR1.2) | 3.2% | 1.1% | −2.1pt | 97.9% | 99.3% |
The effect is biggest for people with a small edge. At zero edge, 80%+ fail either way; with a strong edge, nearly everyone passes either way.
| Risk per trade | 4%/8% fail rate | 5%/10% fail rate | Diff |
|---|---|---|---|
| 0.50% | 12.4% | 5.7% | −6.7pt |
| 0.75% | 33.3% | 21.6% | −11.7pt |
| 1.00% | 49.4% | 36.8% | −12.6pt |
| 1.25% | 58.6% | 47.0% | −11.6pt |
※ Win rate 50%, RR1.2 fixed
At 1% or more per trade, the wider configuration clearly pays off.
5%/10% wins in dollars, 4%/8% wins per dollar
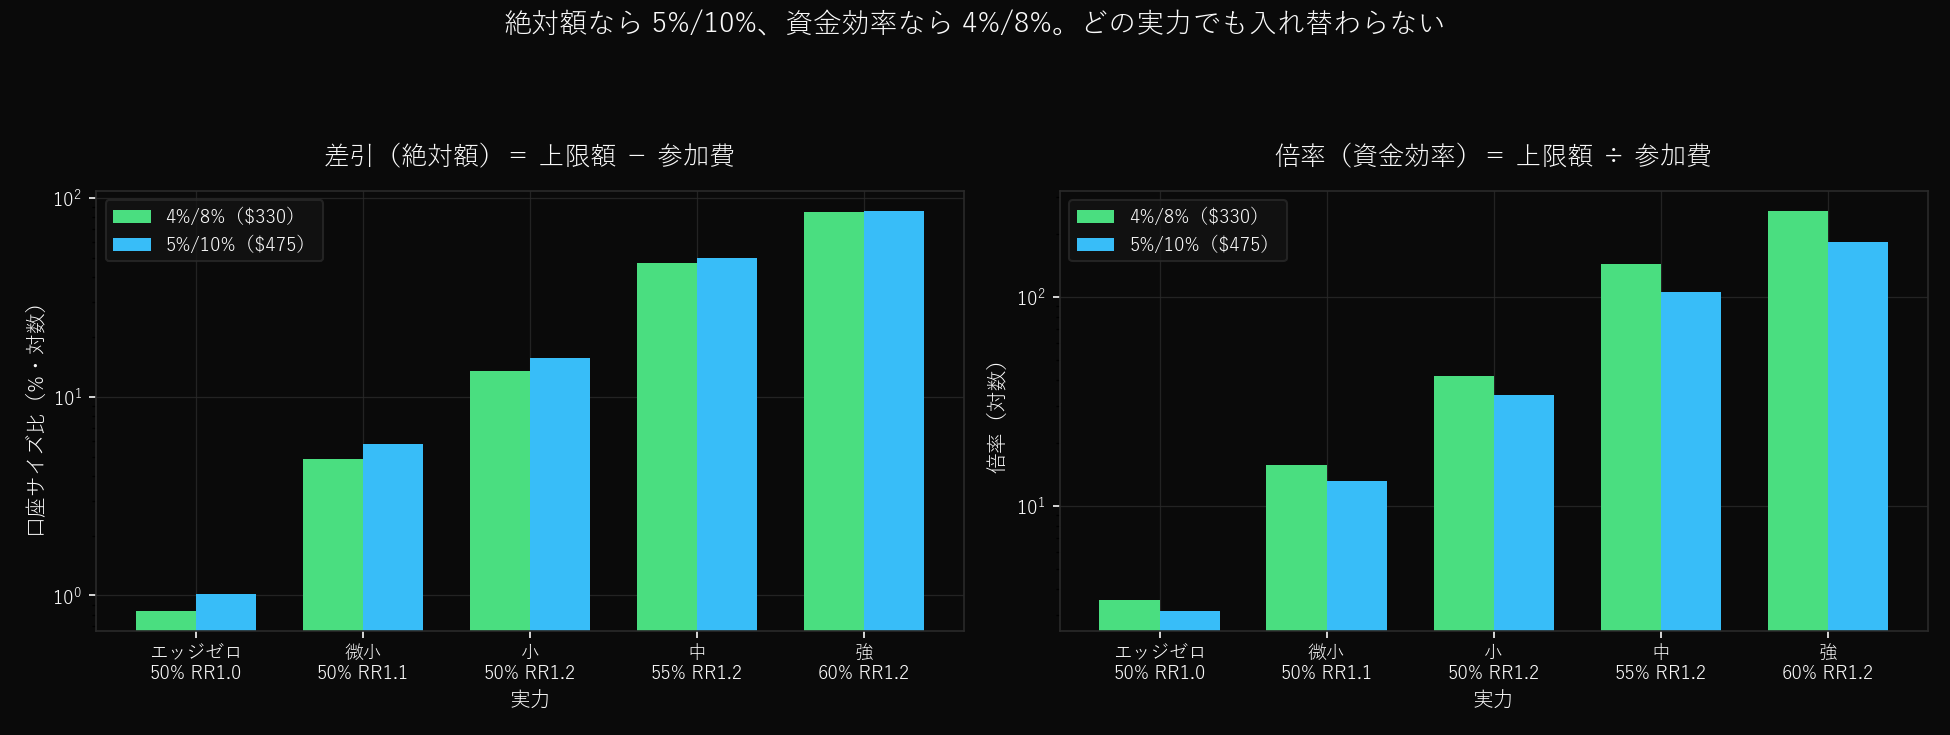
| Skill | 4%/8% net | 5%/10% net | 4%/8% multiple | 5%/10% multiple |
|---|---|---|---|---|
| Zero edge | +0.838% | +1.017% | 3.54x | 3.14x |
| Tiny | +4.862% | +5.762% | 15.73x | 13.13x |
| Small | +13.483% | +15.586% | 41.86x | 33.81x |
| Medium | +46.868% | +49.655% | 143.02x | 105.54x |
| Strong | +84.867% | +86.274% | 258.17x | 182.63x |
※ Net = expected payout (the maximum you should pay) − fee, as a % of account size
The ranking never flips. The fail rate improves by up to 12 points, but the price rises 44%.
On a $950 budget you can buy 1.44 units of 4%/8%. One 5%/10% gives +1.017% net; 1.44 units of 4%/8% give +1.207%. But running several accounts with the same method at the same time isn't independent; when one blows up, they blow up together, so the real diversification benefit is smaller.
In the 1-year simulation below (rebuy after failing, refund on the 4th payout, September 27 list prices), the two configurations come out nearly even, with 5%/10% slightly ahead at 1% or more.
The risk of holding positions
Moneta judges everything on equity, so unclosed floating losses count toward the fail line.
| $100K | 4%/8% | 5%/10% |
|---|---|---|
| Max loss (static) | Fail below $92,000 | Fail below $90,000 |
| Daily loss room | $4,000 | $5,000 |
| Floating-loss trigger per symbol (funded) | $2,000 | $3,000 |
Holding through rollover shrinks the next day's room
The daily fail line is set by a snapshot at 22:00 UTC (7:00 JST) each day. Take the higher of balance and equity, subtract the daily loss amount, and that's the next day's fail line; breaches are judged on equity. Official example ($100K, 4% daily):
| At rollover | Balance | Equity | Fail line | Real room the next day |
|---|---|---|---|---|
| Flat | $100,000 | $100,000 | $96,000 | $4,000 |
| Holding +$1,000 floating profit | $100,000 | $101,000 | $97,000 | $3,000 (from balance) |
| Holding −$1,000 floating loss | $100,000 | $99,000 | $96,000 | $3,000 (from current equity) |
The absolute floating P&L at rollover comes straight out of the next day's room. Carry a floating profit and the unrealized gain lifts the fail line, so if the trade just returns to entry you have $3,000 left. The same $1,000 costs 25% of the room on 4%/8% and 20% on 5%/10%. If you swing trade, hold over weekends, or hold through news, choose 5%/10%. Moneta officially advises against trading around rollover at all (spreads widen).
Floating-loss trigger per symbol: 2% vs 3%
Rough guide at $100K, EURUSD (1 pip = $10 per lot):
| 4%/8% ($2,000) | 5%/10% ($3,000) | |
|---|---|---|
| Adverse move one lot can take | 200 pips | 300 pips |
| Up to a 50-pip adverse move | 4 lots | 6 lots |
| Up to a 100-pip adverse move | 2 lots | 3 lots |
| One lot after the cap (1.5% = $1,500) | 150 pips | 150 pips |
It's judged per trade idea, not per entry. Three entries of 0.7% add up to 2.1%, which trips the trigger on 4%/8%. If you scale into one symbol, add to trend trades while in drawdown, or hold through news, that difference alone is a reason to pick 5%/10%. If you trade one position with a fixed stop and close the same day, it barely matters. This trigger is a funded-account rule, so it only matters after both phases.
What to watch on Instant (standard)
How the 5% trailing line moves
Example with a $10K account:
| Situation | Reference (high) | Loss line |
|---|---|---|
| Start | $10,000 | $9,500 |
| Floating profit briefly reaches $10,300 | $10,300 | $9,785 |
| Closed, balance $10,200 | $10,300 (the high stays) | $9,785 |
| Balance reaches $10,500 | $10,500 | Locks at $10,000 |
A floating-profit peak pushes the reference up. If you let $300 of floating profit come back without taking it, only the loss line stays $285 higher. Once you reach +5%, it behaves like a static drawdown: fail if you drop below the starting balance. Accounts bought before July 2, 2026 have 6%.
The 15%/20% consistency rule
If "one day's profit ÷ total profit" exceeds the chosen %, the payout is put on hold. Nothing is confiscated; once further trading brings the ratio down you can withdraw, and it resets with each payout. To withdraw $1,000 under the 20% rule you need at least 5 business days; under 15%, 7 or more. Make $500 in one news spike and you have to build total profit to $2,500 before you can withdraw.
Instant fail at 1% floating loss
Instant can't be used at 1% per trade. Just before the stop hits, the floating loss including costs exceeds 1% of the account, so accounts bought on or after September 21, 2026 fail right there. Even with the stop at exactly 1%, spread or slippage can push it over. Accounts bought earlier stay on the old rule: close-out at 2%, then a 1.5% cap.
Is Instant Pro worth buying?
The yardstick: the maximum you should pay
For a trader of a given skill, compute the expected amount you receive by the end (zero if you fail; profit × split if you survive). That number is the break-even fee. If the price is below it, buy; if above, it's overpriced.
We ran a 40,000-run Monte Carlo at $100K, 88% split, 1% per trade, 3 trades a day, 8% trailing.
Positive even at zero edge, but thin
Even for a zero-EV coin flip (50% win rate, RR1.0), the expected payout is positive. You lose only the fee if you lose, and you collect your split of the profits if you win: the same shape as a call option. Over 60 business days the fair price came out to $2,751; over 120 business days the maximum was 2.755% of the account.
| Instant Pro price | Fee (% of account) | Multiple (maximum ÷ price) |
|---|---|---|
| List $5,300 | 5.300% | 0.52x |
| 50% off $2,650 | 2.650% | 1.04x |
| 50% off + 0.01% cost per trade | 2.650% | 0.82x (expected $2,173) |
The margin is only 0.105% of the account ($105), and costs wipe it out quickly.
| Cost per trade | Instant Pro net | Moneta 2-Step net |
|---|---|---|
| 0.000% (theoretical) | +$105 | +$838 |
| 0.010% | −$477 | +$430 |
| 0.020% | −$1,050 | +$185 |
| 0.050% | −$2,128 | −$197 |
A cost of 0.01% per trade, $10 on $100K (about 1 pip on 1 lot of EURUSD), turns Instant Pro negative.
You start 3.01% behind the moment you buy
The fee is 2.65% of the account, but you only receive 88% of profits, so you have to make 3.01% on the account to earn it back.
Fee ÷ (account size × split) = break-even $2,650 ÷ ($100,000 × 88%) = 3.01%
| Program | Fee (% of account) | Split | Break-even (% of account) |
|---|---|---|---|
| Moneta Instant Pro | 2.650% | 88% | 3.01% |
| Moneta 2-Step 5%/10% | 0.475% | 88% | 0.54% |
| Fintokei ProTrader | 0.467% | 80% | 0.58% |
Only Instant Pro's hole is 5x+ deeper, and 38% of the road to the +8% lock goes to earning back the fee. Buy at list and the hole is 6.02%.
The 4% daily profit cap
When daily profit reaches 4% of the account, all positions are closed automatically and you can't trade until the next day. With the 88% split, the most you can bank in a day is 3.52% of the account, or $3,520 on $100K. Spend your best possible day entirely on the fee and you're left with $870. The cap clips the top of the distribution for strategies that make big moves in one go. If you stack 0.5%–1% a day, you'll rarely touch 4%.
What the trailing drawdown takes away
We ran the same trade sequence side by side, changing only the drawdown rule.
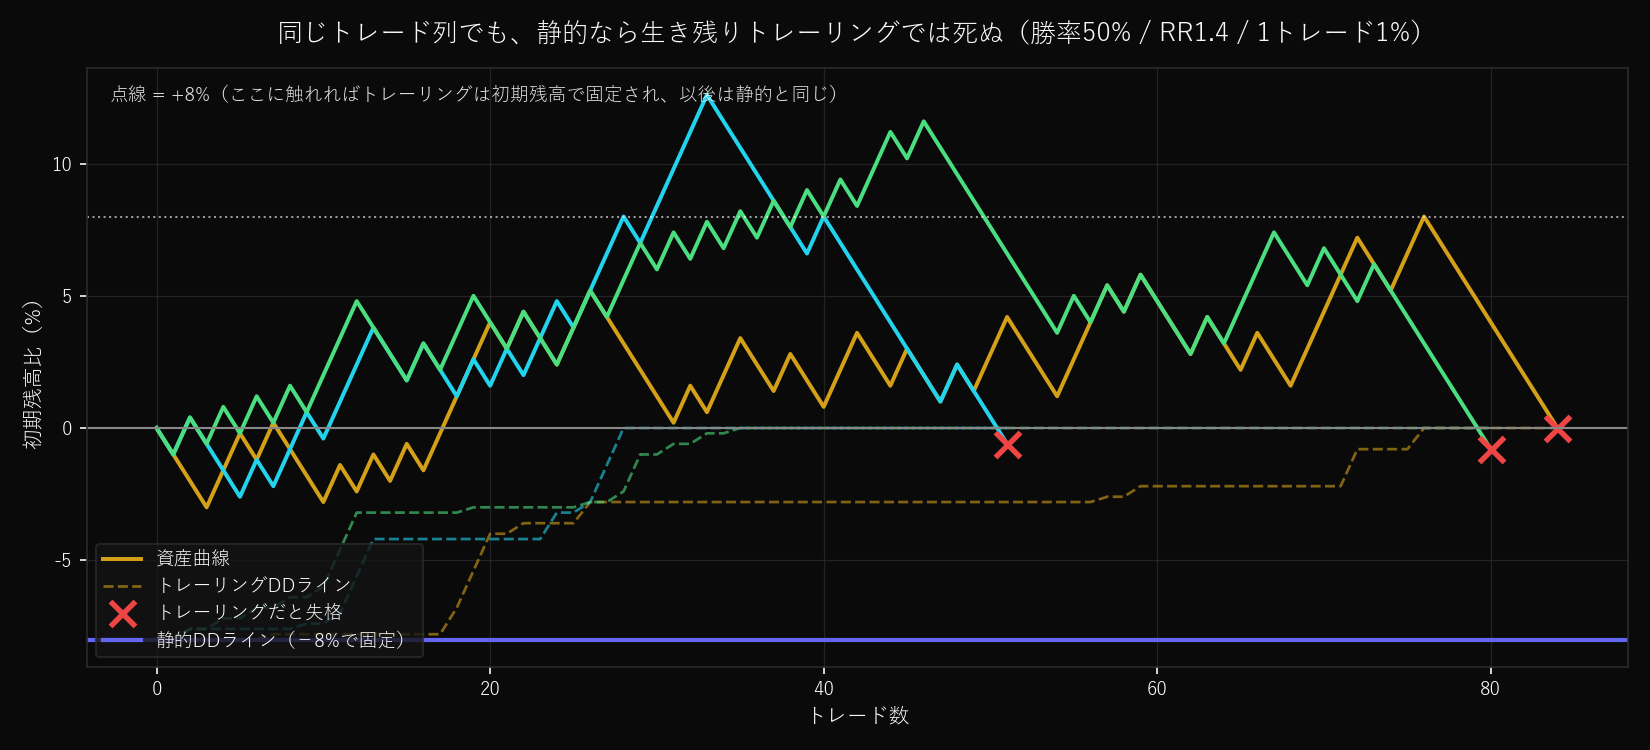
None of the three paths ever touched the static 8% line (blue horizontal line), but all three failed under trailing. The middle one ran up to +12% and then failed on a drop back below entry. Floating profit isn't "money you've made"; it's where your new fail line sits.
Fixing expected value at +0.20r per trade and varying only win rate and RR:
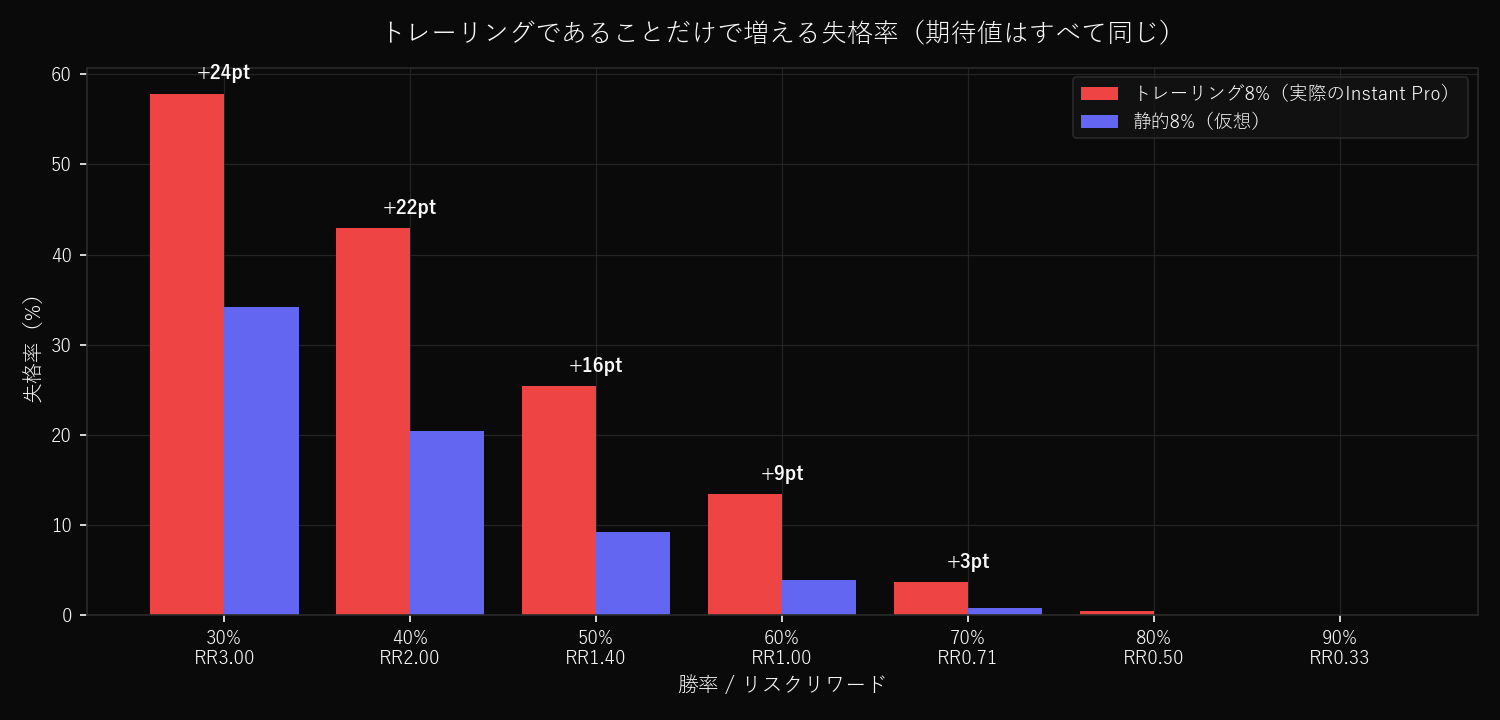
| Win rate | RR | Fail rate (trailing 8%) | Fail rate (static 8%) | Diff |
|---|---|---|---|---|
| 30% | 3.00 | 57.8% | 34.2% | +23.7pt |
| 40% | 2.00 | 42.9% | 20.5% | +22.5pt |
| 50% | 1.40 | 25.4% | 9.2% | +16.2pt |
| 60% | 1.00 | 13.4% | 3.9% | +9.5pt |
| 70% | 0.71 | 3.6% | 0.8% | +2.9pt |
| 80% | 0.50 | 0.5% | 0.1% | +0.4pt |
| 90% | 0.33 | 0.0% | 0.0% | ±0pt |
A trailing drawdown selectively kills rough equity curves. Breakout styles that take small losses and let winners run are the worst match. The gap only exists until the line locks at +8%; 67–100% of failures happened before the lock.
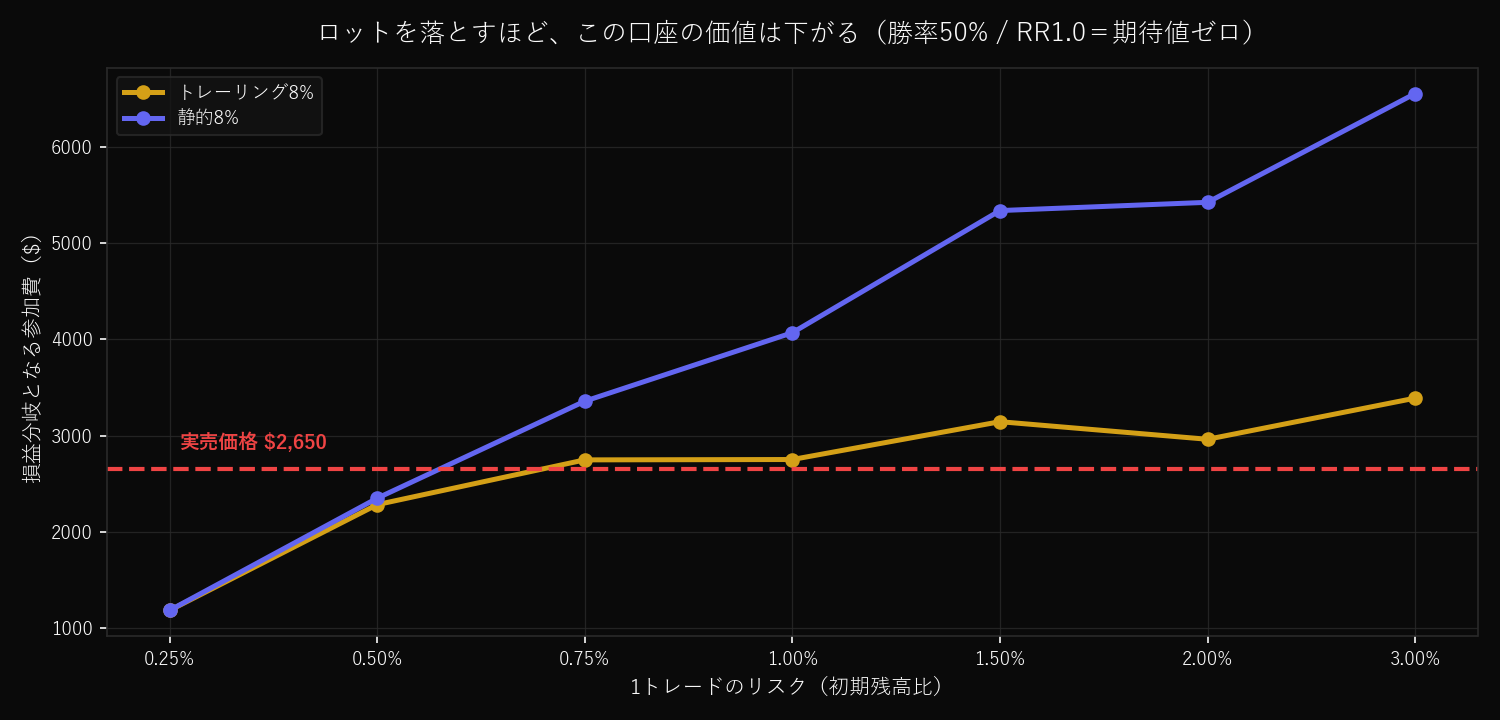
| Risk per trade | Maximum (trailing) | Maximum (static) | Cost of trailing |
|---|---|---|---|
| 0.25% | $1,183 | $1,183 | $0 |
| 0.50% | $2,282 | $2,348 | $66 |
| 0.75% | $2,747 | $3,357 | $610 |
| 1.00% | $2,751 | $4,068 | $1,317 |
| 2.00% | $2,961 | $5,423 | $2,462 |
The bigger you size, the more trailing costs you, but the maximum itself also rises with size. Sizing small removes the cost, but at 0.25% the account is worth $1,183, clearly overpriced at $2,650. You'd be paying for room you don't use, so if you size small there's no point buying an instant account.
How much should you pay at your win rate and RR?
Maximum at $100K, 88% split, 1% per trade, 3 trades a day, 60 business days, 8% trailing:
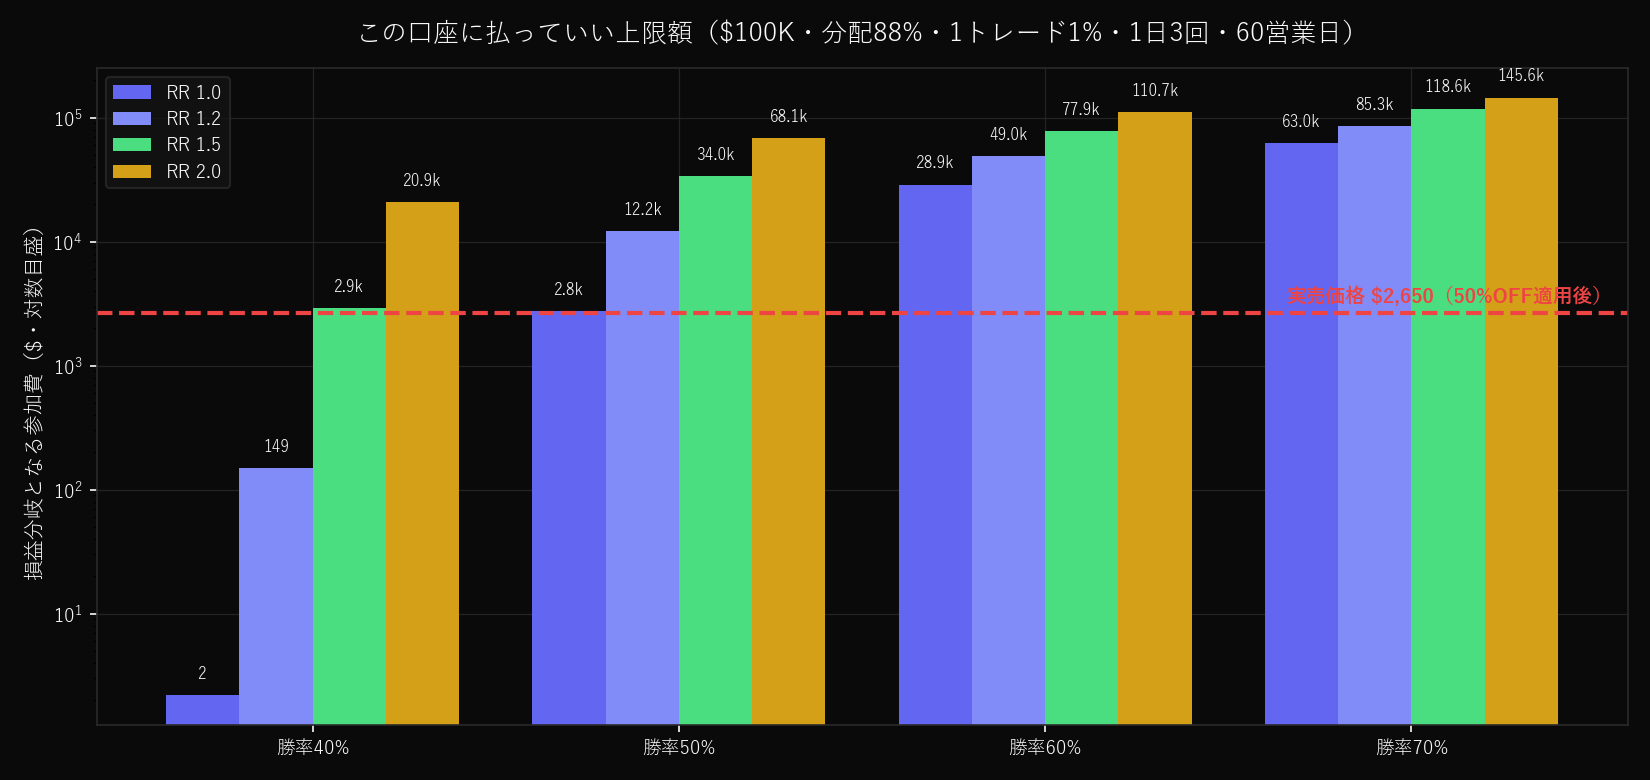
| Win rate | RR1.0 | RR1.2 | RR1.5 | RR2.0 |
|---|---|---|---|---|
| 40% | $2 | $149 | $2,896 | $20,941 |
| 50% | $2,751 | $12,214 | $33,972 | $68,144 |
| 60% | $28,907 | $48,960 | $77,946 | $110,674 |
| 70% | $63,002 | $85,349 | $118,646 | $145,640 |
The $2,650 price line runs just above 50% win rate, RR1.0. At 40% with RR1.2 or less, it's worth almost nothing.
Next to two-phase programs (Moneta 2-Step, Fintokei)
Fees and maximums are expressed as a % of account size, over 120 business days. Instant is funded from day one; evaluation programs start late by the days spent passing.
| Program | DD | Type | Daily | Target | Split | List price | Discount | Fee (% of account) |
|---|---|---|---|---|---|---|---|---|
| Moneta Instant Pro $100K | 8% | Trailing | 4% | None | 88% | $5,300 | 50% off | 2.650% ($2,650) |
| Moneta 2-Step 5%/10% $100K | 10% | Static | 5% | 5%→10% | 88% | $950 | 50% off | 0.475% ($475) |
| Fintokei ProTrader Sapphire | 10% | Static | 5% | 8%→6% | 80% | ¥109,800 | 15% off (assumed) | 0.467% (¥93,330 / ¥20M) |
Fintokei's 15% off is an assumption. There's no standing 15% coupon; it's "if a similar discount existed." At the ¥109,800 list price (0.549%), Fintokei's multiple drops from 3.11x to 2.64x, still far above Instant Pro's 1.04x.
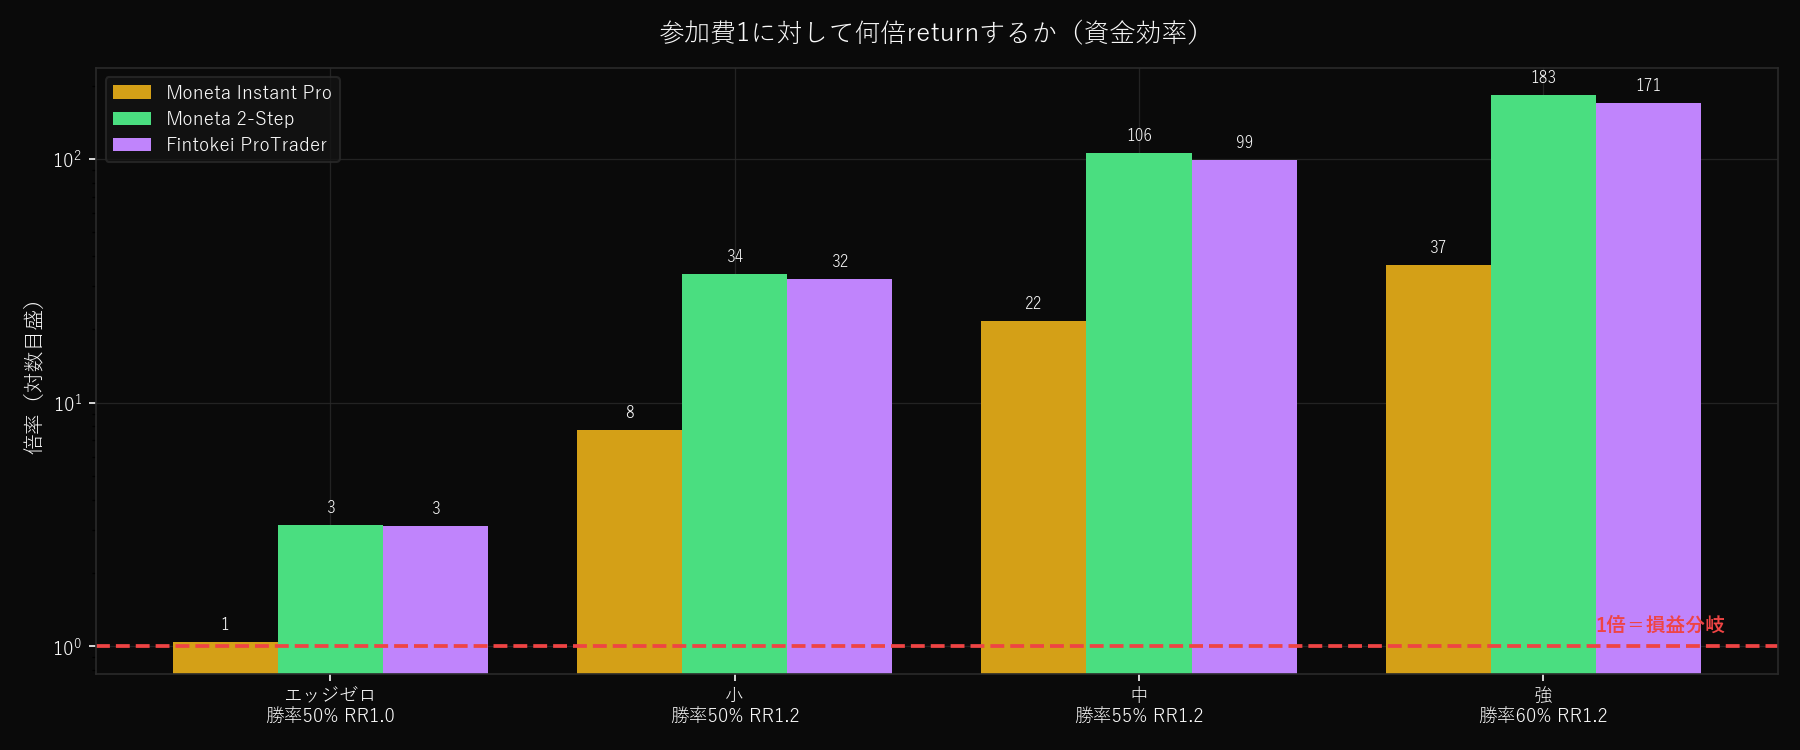
Zero-edge trader
| Program | Fee | Reach funded | Days to funded | Maximum | Net | Multiple |
|---|---|---|---|---|---|---|
| Moneta Instant Pro | 2.650% | 100% | Day 1 | 2.755% | +0.105% | 1.04x |
| Moneta 2-Step | 0.475% | 32.4% | 45 days | 1.492% | +1.017% | 3.14x |
| Fintokei ProTrader | 0.467% | 34.3% | 41 days | 1.452% | +0.985% | 3.11x |
Only a third pass the two-phase programs, but the fee is under a fifth, so they win decisively on efficiency.
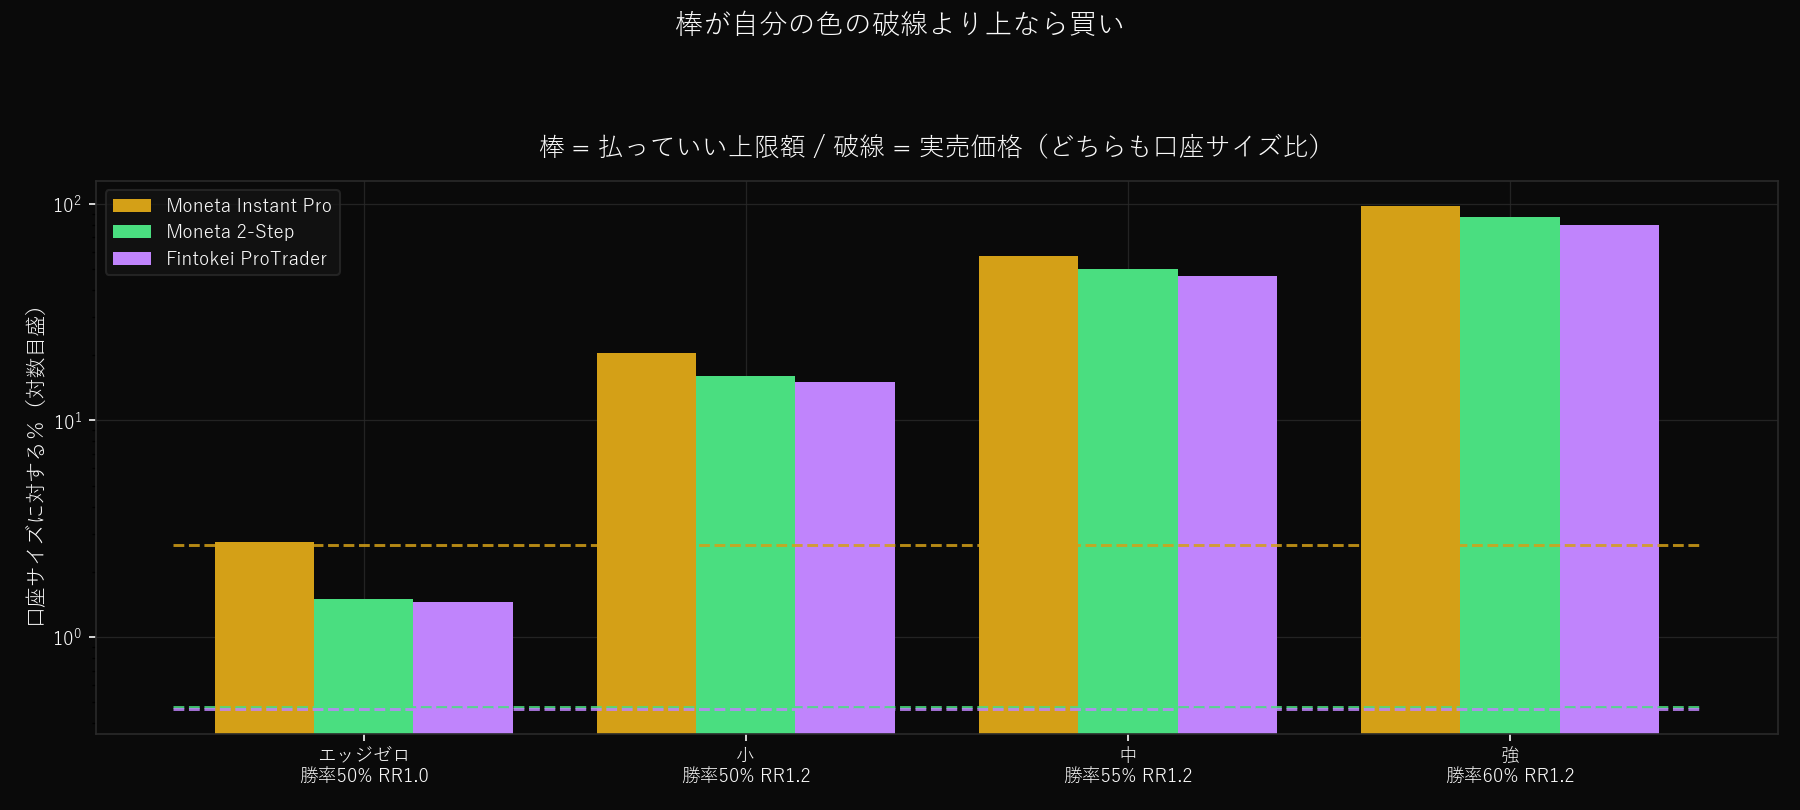
Trader with an edge (60% win rate, RR1.2)
| Program | Maximum | Net | Multiple |
|---|---|---|---|
| Moneta Instant Pro | 97.4% | +94.8% | 37x |
| Moneta 2-Step | 86.7% | +86.3% | 183x |
| Fintokei ProTrader | 79.6% | +79.2% | 171x |
In absolute dollars, Instant Pro is highest, because it uses all 120 business days funded. But by multiple the two-phase programs are 5x more efficient, and the gap doesn't shrink as edge rises. The only reason to buy Instant Pro is time, and you should know you're paying 5x+ for speed.
Moneta 2-Step vs Fintokei
- The targets run in opposite order. Moneta is 5%→10% (back-loaded), Fintokei 8%→6% (front-loaded). Fintokei reaches funded more often (34.3% vs 32.4%) and 4 days sooner, while Moneta's 88% split gives it the higher final payout.
- The 3% risk caps work differently. Moneta judges floating loss on one symbol; Fintokei judges the total of all open positions (any symbol, any direction). An EA holding several pairs at once has an easier time on Moneta.
- Fintokei has no consistency rule by default, though a 40% rule may be applied at payout at its discretion.
- Fintokei bans running someone else's commercial or free EA without adjustment. Self-built EAs, or EAs whose parameters you've tuned yourself, are fine.
- Fintokei is yen-denominated, fully Japanese, and trades directly from TradingView. Martingale was removed from its banned list on July 28, 2025. Its split can rise to 100% through its loyalty program (not in the model).
Compared with Blueberry's instant accounts
Next to Blueberry Funded, another "no evaluation, funded immediately" option. Prices were measured at both firms' checkouts on September 10, 2026. The Blueberry side assumes BERRY15 (15% off), but BERRY15 has ended; as of October 12 the code is BERRY22 (22% off, first purchase). We haven't confirmed whether BERRY22 works on Instant Elite / Lite. The Moneta side assumes TOKONATSU50.
Blueberry's banner code PRIME50 (50% off) is Prime 2-Step only; entering it for Instant Elite returns coupon "prime50" is not applicable to selected products (PRIME30, FLEX30, PRIMEPASS also fail).
| Blueberry plan ($100K) | List | Code that worked | Paid (Sep 10) |
|---|---|---|---|
| Prime 2-Step | $812 | PRIME50 (50%) | $406 |
| Flex 1 Step | $835 | FLEX30 (30%) | $584.50 |
| 1-Step | $605 | BERRY15 (15%) | $514.25 |
| Instant Elite | $2,800 | BERRY15 (15%) | $2,380 |
| Instant Lite | $785 | BERRY15 (15%) | $667.25 |
| Option | List ($10K / $100K) | Code | Discounted ($10K / $100K) | Max DD | DD type | Daily DD | Split | Daily profit cap |
|---|---|---|---|---|---|---|---|---|
| Moneta Instant Pro | $500 / $5,300 | TOKONATSU50 | $250 / $2,650 | 8% | Trailing | 4% | 88% | 4% (pauses) |
| Blueberry Instant Elite | $400 / $2,800 | BERRY15 | $340 / $2,380 | 10% | Trailing lock | None | 80% | None |
| Blueberry Instant Lite | $139 / $785 | BERRY15 | $118.15 / $667.25 | 4% | Trailing lock | 2% | 80% | None |
Both firms' drawdowns trail and lock at the starting balance. Floating profit moves the line too, so a brief unrealized high is enough to lock it in.
Effective DD room: accounting for the loss/profit asymmetry
Drawdown is judged on the whole account, but you only receive your split. So we compare effective DD room = account size × max DD % × split.
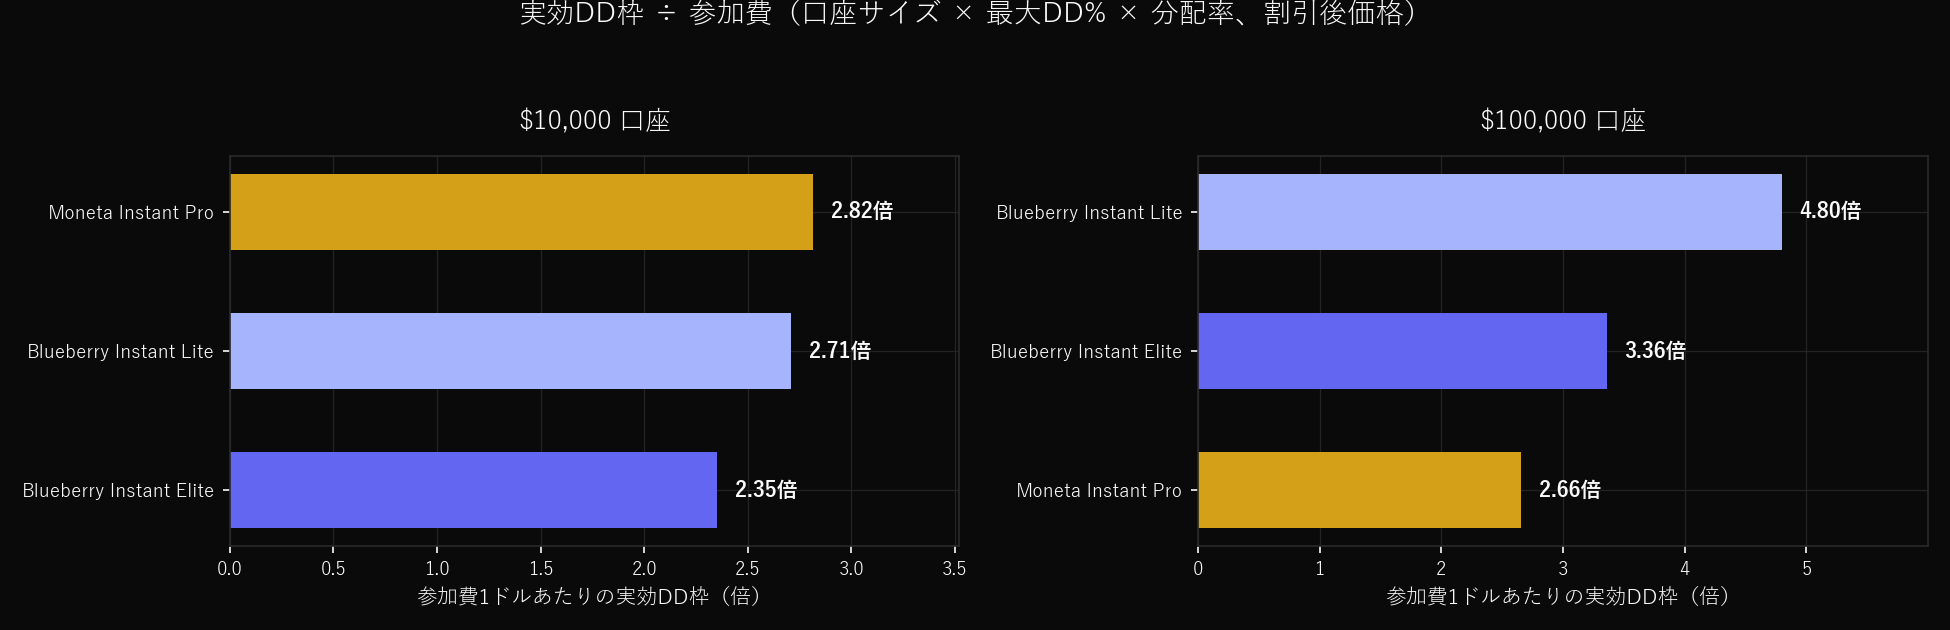
$10,000 account
| Option | Fee | Total room | Split | Effective room | Effective room ÷ price | Break-even |
|---|---|---|---|---|---|---|
| Moneta Instant Pro | $250 | $800 | 88% | $704 | 2.82x | 2.84% |
| Blueberry Instant Lite | $118.15 | $400 | 80% | $320 | 2.71x | 1.48% |
| Blueberry Instant Elite | $340 | $1,000 | 80% | $800 | 2.35x | 4.25% |
$100,000 account
| Option | Fee | Total room | Split | Effective room | Effective room ÷ price | Break-even |
|---|---|---|---|---|---|---|
| Blueberry Instant Lite | $667.25 | $4,000 | 80% | $3,200 | 4.80x | 0.83% |
| Blueberry Instant Elite | $2,380 | $10,000 | 80% | $8,000 | 3.36x | 2.97% |
| Moneta Instant Pro | $2,650 | $8,000 | 88% | $7,040 | 2.66x | 3.01% |
The ranking flips with size. Blueberry Elite goes from $400 to $2,800 (10x the size for 7x the price); Moneta Instant Pro goes from $500 to $5,300 (10.6x). Blueberry gets cheaper as you go bigger; Moneta is cheaper small.
Risk cap per trade
| Option | Cap per trade idea | If you hit it |
|---|---|---|
| Moneta Instant Pro | Floating loss on one symbol (threshold above), then 1.5% per idea | All positions auto-closed + paused for the day. Fail above 1.5% after that. Lifting the cap takes 14 days + 20 trades on another account |
| Moneta Instant (standard) | Floating loss on one symbol 1% | Instant fail (accounts bought on/after Sep 21, 2026) |
| Blueberry Instant Elite / Lite | 1.5% (of initial account size) | Account closed immediately, no warning |
Blueberry counts a same-direction re-entry on the same or a correlated symbol within 10 minutes of a stop-out as the same idea.
Rule differences
| Moneta Instant Pro | Blueberry Instant Elite | |
|---|---|---|
| EA | Self-built only (fully automated OK; commercial/third-party EAs banned) | Allowed (with conditions) |
| Platforms | MT5 / Match-Trader | MT5 / TradeLocker |
| Martingale / grid | Banned | Allowed (accounts bought on/after Mar 12, 2026) |
| Copy trading | Only between your own Moneta accounts | No copying others; your own accounts OK |
| News | Allowed | Not allowed (high-impact events) |
| Consistency rule | None | None |
| Minimum trading days | None | 5 days (only days with 0.5%+ profit on balance) |
| Leverage | FX 1:30 | FX 1:30 |
If you trade through news, Moneta is your only option here. If you use martingale or grid, Blueberry. Neither offers MT4.
Monte Carlo (40,000 runs, 60 business days)
Daily P&L is normally distributed as a share of the starting balance (SD 1%). Each plan's daily loss, max DD (trailing lock), daily profit cap, and consistency rule are modeled. The same random sequence is applied to every plan (a paired comparison).
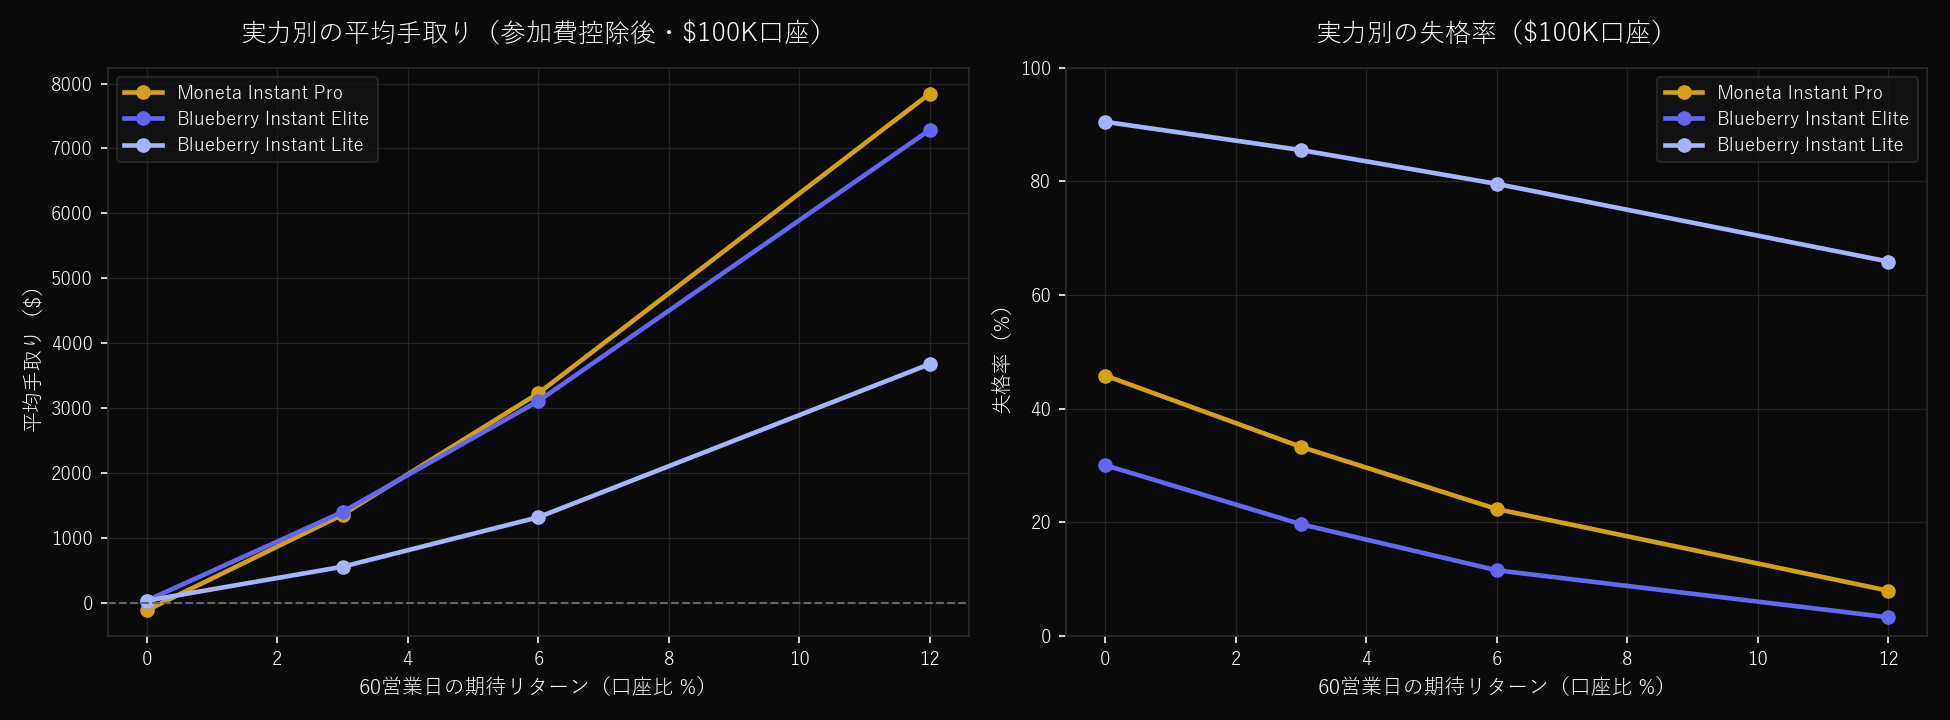
$100,000 account
| Skill (60 days) | Moneta Instant Pro | Blueberry Instant Elite | Blueberry Instant Lite | |
|---|---|---|---|---|
| ±0% | Avg take-home | −$120 | +$30 | +$29 |
| Chance of profit | 32.3% | 34.2% | 9.4% | |
| Fail rate | 45.9% | 30.1% | 90.5% | |
| +3% | Avg take-home | +$1,354 | +$1,396 | +$552 |
| Chance of profit | 46.8% | 49.2% | 14.3% | |
| Fail rate | 33.3% | 19.7% | 85.5% | |
| +6% | Avg take-home | +$3,226 | +$3,106 | +$1,315 |
| Fail rate | 22.4% | 11.6% | 79.6% | |
| +12% | Avg take-home | +$7,847 | +$7,287 | +$3,677 |
| Fail rate | 8.0% | 3.3% | 65.9% |
With a small edge Blueberry Instant Elite leads; at +6% and above Moneta Instant Pro overtakes it (the 88% vs 80% split outweighs the fail-rate gap). Blueberry Elite has the lower fail rate at every level.
$10,000 account
| Skill (60 days) | Moneta Instant Pro | Blueberry Instant Elite | Blueberry Instant Lite | |
|---|---|---|---|---|
| ±0% | Avg take-home | +$3 | −$99 | −$49 |
| Fail rate | 45.9% | 30.1% | 90.5% | |
| +3% | Avg take-home | +$150 | +$38 | +$4 |
| Fail rate | 33.3% | 19.7% | 85.5% | |
| +6% | Avg take-home | +$338 | +$209 | +$80 |
| Fail rate | 22.4% | 11.6% | 79.6% | |
| +12% | Avg take-home | +$800 | +$627 | +$316 |
| Fail rate | 8.0% | 3.3% | 65.9% |
At $10K, Moneta Instant Pro has the highest average take-home at every skill level.
Blueberry Instant Lite: the rules cap your size
Lite's 90.5% fail rate is extreme because a 1%-daily-volatility position is sitting on an account with a 4% max DD and 2% daily limit. Those rules cut the size you can carry in half, so we also ran every plan at half size (0.5% daily volatility, skill scaled down proportionally).
| All plans at half size (skill = +6% over 60 days at full size) | Avg take-home | Chance of profit | Fail rate | Payout hold rate |
|---|---|---|---|---|
| Moneta Instant Pro | +$393 | 49.6% | 1.1% | – |
| Blueberry Instant Elite | +$387 | 50.0% | 0.1% | – |
| Blueberry Instant Lite | +$2,004 | 66.3% | 22.4% | 62.7% |
| Instant Lite at half size | Avg take-home | Chance of profit | Fail rate | Payout hold rate |
|---|---|---|---|---|
| Full-size equivalent ±0% | +$483 | 37.5% | 45.9% | 41.9% |
| Full-size equivalent +6% | +$2,004 | 66.3% | 22.4% | 62.7% |
| Full-size equivalent +12% | +$4,105 | 87.5% | 8.0% | 63.9% |
At half size, Lite wins easily (its fee is under a quarter of the others). Instant Pro and Instant Elite drop to about a 1% fail rate, but you're paying $2,650 and $2,380 for drawdown room you don't use. Lite does have a 15% consistency check, and at half size 62.7% have their first payout put on hold. The official wording is "paused rather than declined… Nothing is deducted," so we don't subtract it from take-home and report the hold rate separately. At full size the hold rates were 8.6% (±0%), 12.3% (+3%), 15.8% (+6%), and 19.7% (+12%).
The break-even on price and split alone
Covering the $2,650 − $2,380 = $270 fee gap with an 8-point split difference takes $3,375 of profit (3.4% of $100K). If you can beat 3.4%, Moneta Instant Pro; if not, Blueberry Instant Elite. But if your method hits the 4% daily cap, don't pick Moneta even if you can beat 3.4%.
1-year expected value simulation
From here, every plan is run for a year under the same conditions. Prices are September 27 list prices (no coupon), and the 1-Step is the pre-change account (6% static, $780).
Assumptions
Fixed
- 1 year (250 business days), up to 3 trades a day, take-profit and stop-loss 1:1
- Daily loss capped at 2.5% of the starting balance for every plan (if the next loss would push past 2.5%, no more trades that day)
- Risk per trade, floating loss, and daily loss never exceed 3%
- Size fixed at r% of the starting balance, one position at a time
- Cost = 5% of risk per trade (+0.95R on a win, −1.05R on a loss). For USDJPY that's a 30-pip stop/target at 1.5 pips round-trip cost, or 40 pips at 2 pips
- Rebuy the same plan after failing, no scaling, payouts every 14 days, profit left in the account at year-end not counted
- 20,000 runs per condition
Varied
- Plan
- Skill: win rate 50% (zero) / 52% (small) / 55% (medium) / 58% (strong)
- Risk per trade r (0.5%, 1.0%, 1.5%)
- How much profit to leave in the account at each payout (the best amount was chosen per plan)
Not in this model
- Instant Pro's "auto-close and pause until the next day when daily profit hits 4%." At 1.5% per trade it only bites on days with 3 straight wins (+4.275%)
- Instant's consistency rule is modeled as "best day ÷ sum of winning days." Officially the denominator is "total profit," so over periods with losing days the official rule is a little stricter
- The 5-minute news window, changes in daily room from floating P&L carried over, and swaps
At this sizing (up to 1.5% per trade, one position), the floating-loss-per-symbol rule on plans other than Instant never triggers. Instant was calculated as 20%/88% ($877).
The formulas
With 1:1 TP/SL and a cost of 0.05R, a win is +0.95R and a loss is −1.05R.
EV per trade = p × 0.95R − (1 − p) × 1.05R = (2p − 1.05) × R
| Skill | Win rate p | EV per trade |
|---|---|---|
| Zero | 50% | −0.05R |
| Small | 52% | −0.01R |
| Medium | 55% | +0.05R |
| Strong | 58% | +0.11R |
1-year EV = average payouts received + average fees refunded − average fees paid
- Payouts received = amount withdrawn × split (88% on every plan)
- Fees refunded: 2-Step and 1-Step refund in full on the 4th payout. Instant and Instant Pro have no refund
- Fees paid = fee × number of purchases in the year
Risking 1% ($1,000) on $100K with a 1.5-pip round-trip cost on USDJPY means 5 lots with a 30-pip stop/target. A win is +$950, a loss −$1,050, and at a 55% win rate each trade is worth +$50. Even on 1:30 plans, 5 lots ($500K) is 5x effective leverage, within the limit. Lot size, effective leverage, and cost are worked through in the 4-firm comparison.
0.5% per trade: average 1-year take-home minus fees
| Skill | 2-Step 5%/10% | 2-Step 4%/8% | 1-Step (pre-change) | Instant (20%/88%) | Instant Pro |
|---|---|---|---|---|---|
| Zero | −$2,515 | −$2,389 | −$2,964 | +$57 | −$24,956 |
| Small | −$889 | −$781 | −$35 | +$5,915 | −$15,045 |
| Medium | +$6,605 | +$6,531 | +$9,738 | +$17,017 | +$3,035 |
| Strong | +$21,920 | +$21,639 | +$26,527 | +$32,210 | +$23,278 |
At 0.5%, a losing trade's floating loss is 0.525%, so Instant's 1% rule never triggers. At this size Instant is #1 at every skill level.
1.0% per trade
| Skill | 2-Step 5%/10% | 2-Step 4%/8% | 1-Step (pre-change) | Instant (20%/88%) | Instant Pro |
|---|---|---|---|---|---|
| Zero | −$3,156 | −$3,106 | −$2,695 | N/A | −$49,166 |
| Small | +$2,954 | +$2,544 | +$5,060 | N/A | −$27,627 |
| Medium | +$22,016 | +$20,234 | +$24,796 | N/A | +$9,838 |
| Strong | +$53,040 | +$50,501 | +$55,207 | N/A | +$49,266 |
1.5% per trade
| Skill | 2-Step 5%/10% | 2-Step 4%/8% | 1-Step (pre-change) | Instant (20%/88%) | Instant Pro |
|---|---|---|---|---|---|
| Zero | −$1,401 | −$1,736 | +$118 | N/A | −$58,199 |
| Small | +$6,686 | +$5,699 | +$9,810 | N/A | −$32,906 |
| Medium | +$28,135 | +$25,301 | +$32,165 | N/A | +$9,945 |
| Strong | +$61,787 | +$58,506 | +$65,062 | N/A | +$55,499 |
The pre-change 1-Step ranked #1 at every skill level at 1% and 1.5%, because a single step gets you funded sooner and leaves more days in the year to earn. But the new 1-Step you can buy today fails at 1% floating loss, so the 1% and 1.5% columns don't apply to it. Among plans you can buy today, 2-Step 5%/10% is #1 at every skill level at 1% and above.
Why the plans differ
| Plan | What drives it |
|---|---|
| 1-Step (pre-change) | One step, so you get funded sooner. Max loss is tight at 6% but static and doesn't move after payouts. Fee refunded on the 4th payout |
| 2-Step 5%/10% | Widest room (10% static). But Phase 2's 10% target is heavy, so it takes longer to get funded |
| 2-Step 4%/8% | $195 cheaper, but Phase 2 is "make 10% when you can only lose 8%." The bigger you size, the further it falls behind 5%/10% |
| Instant (20%/88%) | No evaluation, fee is 0.877% of the account. Strongest at 0.5% per trade, but the 1% floating-loss fail stops you sizing up. The line rises to the starting balance when a payout is approved |
| Instant Pro | Fee is 5.3% of the account, 6–8x the others. The 8% trailing room and on-demand first payout don't make it back |
On Instant and Instant Pro, the line rises to the starting balance when a payout is approved. After that, your only buffer is the profit you leave in the account. The simulation picks the best amount to leave at each payout for each plan.
Payouts, refunds, and trading from Japan
- Payouts: first payout 14 days after your first trade on the funded account (counted to the minute), then every 14 days, $100 minimum. Only Instant Pro lets you request the first payout any time from $100. 1-Step Daily pays daily. Processing takes 24–48 business hours; KYC is via Sumsub.
- How you're paid: USDC-ERC20 / USDT-ERC20 / USDT-TRC20, or a Moneta Markets trading account (+20% bonus or 2x credit). Payouts to a Moneta Markets account are probably not available to Japanese residents (third-party information). We couldn't confirm Wise or bank transfer in the official help. The help center doesn't state a per-payout cap.
- Refunds: on the 1-Step and 2-Step, the fee is refunded in full on the 4th payout from the same challenge. Instant and Instant Pro have no refund. Accounts that have traded are not refunded for any other reason; untraded accounts can be refunded within 14 days of purchase. Transfers to another program aren't allowed (support answer, October 12).
- Japan: not on the banned list (Iran, Afghanistan, Thailand, Cuba, Myanmar, North Korea, UAE, Venezuela, Vietnam, plus sanctioned countries). No Japanese site or support.
- Payment: Visa / Mastercard / Amex / Apple Pay / Google Pay / crypto (Ethereum, Solana, Tron, Polygon, Arbitrum, BNB, Base, TON, Bitcoin chains).
The operator is Moneta Funded Ltd. (Saint Lucia IBC, registration 2025-00532); the CEO is David Bily, founder of the FX/CFD broker Moneta Markets. It launched on January 13, 2026. Under the terms, Moneta Funded and Moneta Markets are separate companies, and Moneta Funded itself is an unregulated prop firm.
EAs and martingale
The banned-practices page in the official help center (article 12146808, updated September 16, 2026) contains a sentence that can be read as banning "software that trades mechanically by predetermined rules." When the site owner asked support on October 12, the written answer was:
- Fully automated EAs that you developed and own may be used on the standard 2-Step (as long as you follow the risk-management guidelines)
- Martingale, grid/layering, latency arbitrage, and HFT tick-scalping types are not allowed
- Commercial or third-party EAs, signal services, and account-management tools are banned
- The firm can review your trading at any time and ask for proof that you own the EA (source code)
The written confirmation covers the 2-Step; other plans are likely treated the same but this is unconfirmed. Since the page wording is vague, it's safest to confirm in writing with support yourself before running an EA.
Martingale is banned on every plan (increasing size after a loss to win it back; the Japan business developer confirmed this with the firm's technical team on September 9, 2026). Same-size averaging down is conditionally allowed within the floating-loss-per-symbol rule. Hedging, hyperactivity (excessive orders or adding to positions), tick scalping, and one-sided betting are also named as banned. Copy trading is only allowed between your own Moneta Funded accounts.
Reputation
Trustpilot shows 4.5 / 282 reviews (as of October 12, no suspension). Most reviews mention fast payouts ("approved in 3 hours," "received in 6 hours"), so the payout speed looks real.
On the other hand, a cluster of similar negative reviews appeared from June to October 2026:
- Account closed for "document forgery" after 3 payouts, $3,000 held (June 2026)
- Account banned on the 4th payout request, $3,000 unpaid (August 2026)
- Asked for a risk-team interview on the 3rd payout; after declining to disclose the strategy, terminated for "rule optimization and gamification" (July 2026)
- Disputes over drawdown calculations, such as a daily DD breach "without exceeding 3%" (September 2026)
- Passes revoked or funded accounts closed for "too much layering (adding to positions)" or "hyperactivity"
The firm's replies stop at "we found serious violations" with no specifics. The payout terms page is password-protected, so ordinary users can't read it (checked September 9), and the consistency rule appears only in the help center. There's also a clause letting the firm require a video interview at any time. If you run an EA, avoid designs that stack many positions, and check for rule changes with every payout.
Compared with other firms' instant accounts
| Moneta Instant | FundedNext Stellar Instant | Funding Pips Zero | Lark Funding Instant | FundedElite Instant | |
|---|---|---|---|---|---|
| Account sizes | $5K–$100K | $2K–$20K | $5K–$200K | $5K–$100K | $7K–$100K |
| Price ($10K) | $80–$155 ($40–$78 with the 50% code) | - | - | $400 | Varies by configuration |
| Daily DD | 3% | - | 3% | 5% | 3% |
| Max DD | 5% trailing | 6% trailing | 5% trailing | 8% | 6% fixed |
| Split | 60% or 88% | 80% | 95% | 90% | 70–95% |
| Leverage | FX 1:30 | 30x | 1:50 | 1:50 | 1:30–1:100 |
| Consistency | 15% or 20% | - | - | - | - |
Moneta wins on price and maximum account size. It loses on split to Funding Pips (95%) and Lark (90%), its DD is tighter than FundedElite's 6% fixed, and it's the only one with a consistency rule. (Other firms' figures are from this site's guides as of September 2026.)
Which to buy
| Your situation | Pick |
|---|---|
| Risking around 1% per trade, betting on one account | 2-Step 5%/10% |
| Buying many accounts, rebuying after failing | 2-Step 4%/8% |
| Holding overnight, through news, or scaling into one symbol | 2-Step 5%/10% (5% daily, 3% floating-loss trigger) |
| Want to start without an evaluation (the 1% floating-loss rule limits you to 0.5% per trade) | Instant 20%/88% |
| Want to trade news | Instant Pro or Phoenix. Instant Pro has the lowest expected value |
| Want small daily payouts (stop around 0.5%) | 1-Step Daily |
- Don't buy: the new 1-Step (about 2.6x the 2-Step per unit of room, can't risk 1% per trade), Instant's 60% split, Instant Pro $100K.
- If you want to try Instant Pro, start at $10K. Half price helps most on small accounts: at $250 it had 2.82x effective room and a 2.84% break-even, better than any Blueberry instant account. Test the 4% daily cap and execution quality with your own method before sizing up. The Monte Carlo ignores execution quality; the less slippage, the higher your realized edge, and above +6% Moneta overtakes Blueberry, so good fills tilt the verdict toward Moneta.
- If not getting knocked out matters most for an instant account, Blueberry Instant Elite (no daily loss, 10% DD; its fail rate was 10+ points below Instant Pro at every skill level).
FAQ
Q. Is Moneta Funded's expected value positive?
With a 55% win rate (+0.05R per trade), every plan except Instant Pro was positive over the year. At zero skill (50% win rate), Instant at 0.5% per trade (+$57) and the pre-change 1-Step at 1.5% (+$118) roughly broke even; everything else was negative.
Q. How did the 1-Step change in October 2026?
On 1-Step accounts bought after the change, max loss went from 6% static to 5% trailing (also locked at the starting balance when a payout is approved), floating loss of 1% on one symbol is an instant fail, and $100K costs $1,098. Accounts bought before the change keep the old rules. The 2-Step, Instant, and Instant Pro didn't change. A new 1-Step Daily was also added: 3% target, 1% daily, 2% max, daily payouts, $284 for $100K.
Q. 2-Step: 4%/8% or 5%/10%?
5%/10% if you're betting on one account, 4%/8% if you're buying many and rebuying after failing. 5%/10% cuts the fail rate by up to 12.6 points and has the higher expected value per account at every skill level; 4%/8% is more efficient per dollar of fee at every skill level. The ranking doesn't change with skill. If you hold overnight or scale into one symbol, 5%/10%.
Q. Is the 2-Step target really 5% then 10%?
That's what the official help center says: 5% in Phase 1, 10% in Phase 2, the reverse of the usual setup. The targets are the same in both configurations.
Q. Is the 2-Step max loss static?
Yes, in both configurations. At $100K it's fixed at $92,000 (8%) or $90,000 (10%). Instant, Instant Pro, and the new 1-Step trail.
Q. Do I fail if I hit the floating-loss-per-symbol trigger?
On 2-Step and pre-change 1-Step funded accounts, no. That symbol's positions are all closed and trading stops for the day, then a 1.5% per-idea cap applies; exceed that and you fail. The cap lifts after 14 days plus 20 trades on another funded account. On Instant accounts bought on or after September 21, 2026, and on the new 1-Step, 1% is an instant fail.
Q. When did Instant's "instant fail at 1% floating loss" start?
For Instant accounts bought on or after September 21, 2026. When floating loss on one symbol reaches 1% of account size, the account fails with no warning. Accounts bought earlier are on the old rule: close-out at 2%, then a 1.5% cap.
Q. Is the 88% split on Instant automatic?
No. You pick 60% or 88% at purchase, and 88% costs more. 88% overtakes 60% after $136 of profit, so don't pick 60%. Instant Pro, 1-Step, 2-Step, and Phoenix are fixed at 88%.
Q. How is Instant's consistency rule calculated?
If "one day's profit ÷ total profit" exceeds the chosen % (15% or 20%), the payout is put on hold until the ratio comes down through further trading. Nothing is confiscated, and it resets with each payout. It applies only to standard Instant.
Q. Is Instant Pro worth it at half price?
Not if you're buying for expected value. The most a zero-edge trader should pay is 2.755% of the account, so the 5.300% list price is about twice its value. At 50% off (2.650%) it's a 1.04x fair trade, and 0.82x with a 0.01% cost per trade. Two-phase programs come out at 3x+ under the same conditions. The only reason to buy is time: you're funded from day one.
Q. Why does an account have value even at zero expected value?
Because your loss stops at the fee and your profit has no ceiling. It's the same structure as a call option: even when the underlying has zero expected value, the option is worth something. Think of the fee as the price of that option.
Q. What does "trailing locks at the starting balance" mean?
The DD line only keeps rising until it reaches the starting balance. On a $100K Instant Pro the line starts at $92,000; when equity touches $108,000 the line reaches $100,000 and stops there. Note that floating profit moves the line too.
Q. Why do low-win-rate, high-RR methods suffer under trailing drawdown?
Because it judges how rough the path is, not the expected value. A 30% win-rate method runs through losing streaks before a winner arrives, and those streaks eat the distance to the DD line. Before the lock, a big win just pushes the DD line up.
Q. Should I buy a two-phase account with only a ~30% pass rate?
Yes, because the fee is under a fifth. Even a zero-edge trader who passes one time in three gets an expected funded payout 3x the fee. Look at pass rate relative to price.
Q. Fintokei or Moneta 2-Step?
They're nearly even. Discounted fee (0.475% vs 0.467%), 10% static DD, and 5% daily are almost identical; the differences are target order (Moneta 5%→10%, Fintokei 8%→6%) and split (88% vs 80%). Moneta's final payout came out slightly higher (net +1.017% vs +0.985%). If you need yen pricing, Japanese support, and TradingView, Fintokei; if your EA holds several positions at once, Moneta is easier.
Q. Does Blueberry's PRIME50 work on instant accounts?
No. It's Prime 2-Step only; entering it for Instant Elite returns coupon "prime50" is not applicable to selected products. On September 10 only BERRY15 (15% off) worked on instant accounts, and BERRY15 has since been replaced by BERRY22.
Q. Blueberry Instant Elite or Instant Lite?
Elite if you trade full size. Lite's 4% max DD and 2% daily rules cut the size you can carry in half. At half size, Lite's fail rate drops to 22.4% and its average take-home (+$2,004) is far above Elite's (+$387), but 62.7% have their first payout on hold at day 60.
Q. Can I use an EA at Moneta Funded?
Self-built EAs are allowed, even fully automated. Support confirmed this in writing for the 2-Step on October 12, 2026. Martingale, grid/layering, latency arbitrage, and HFT tick-scalping types are not allowed; commercial or third-party EAs, signals, and account-management tools are banned; and you may be asked for proof of ownership (source code).
Q. When and from how much can I withdraw at Moneta Funded?
First payout 14 days after your first trade on the funded account, then every 14 days, $100 minimum. Only Instant Pro allows the first payout any time, and 1-Step Daily pays daily. You're paid in USDC/USDT (ERC20, TRC20) or to a Moneta Markets account.
Q. Does Moneta Funded refund the fee?
On the 1-Step and 2-Step, the fee is refunded in full on the 4th payout from the same challenge. Instant and Instant Pro have no refund. Accounts that have traded aren't refunded for any other reason; untraded accounts can be refunded within 14 days of purchase.
Q. Can I use it from Japan?
Japan isn't on the banned list, so yes. There's no Japanese UI or support, and USDT/USDC is effectively the payout method.
Q. Are there coupons?
As of October 12 the official banner shows monetober40 (40% off, no end date stated). TOKONATSU50 (50% off), distributed by the Japan business developer on note, worked on every program on September 10–12, but we haven't checked it since October. Codes can't be combined and are cleared when you change the configuration, so set everything first and enter the code last.
Q. I want to run this with my own numbers
The scripts are public. For 1-year EV, sim-prop-ev.py with this article's config file (needs Python and numba); for Instant Pro static vs trailing and the maximum price, sim-instant-pro-trailing.py; for the two-phase comparison and the 2-Step configuration comparison, sim-phases-vs-instant.py; for the Blueberry comparison, sim-instant-moneta-vs-blueberry.py (all Python + NumPy, fixed random seed). You can change price (e.g. after a coupon), win rate, RR, and size.
Assumptions and limits (40,000-run Monte Carlo)
- Spreads, commissions, and swaps aren't in the main calculation. Only Instant Pro's cost sensitivity is shown separately.
- The floating-loss-per-symbol trigger, rollover carry, and per-trade-idea risk caps aren't modeled, because trade-level and daily models can't represent the path of floating losses. Every plan looks a bit better than reality.
- The Blueberry comparison uses daily closes, so it misses intraday spikes that would knock an account out. It assumes one payout at the end.
- Minimum profit days aren't modeled.
- The model doesn't retry after failing (the 1-year simulation does rebuy). In reality you can rebuy, so cheaper plans do a little better in practice.
- Wins and losses are assumed independent. Real markets cluster losing streaks, so everything looks a bit better than reality.
- The fee refund on the 4th payout isn't in the 40,000-run model (it is in the 1-year simulation).
- If the discount expires, the conclusion's premise changes. Without 50% off, Instant Pro's fee is 5.300% and, at 0.52x, its expected value is clearly negative.
Related
- 📰 Breaking: Moneta Funded rebuilds the 1-Step (October 2026)
- 🏢 Moneta Funded guide / Compare Moneta Funded plans
- 📊 Expected value: FTMO, The5ers, Fintokei, RZR
- 📊 E8 Markets expected value (incl. E8 Pro)
- 🧭 1-step vs 2-step vs Instant Funding
- 🏆 Best prop firms, September 2026
- 🤖 Prop firm EA rules guide
- 🏢 Fintokei guide
- 🧾 Prop firm tax guide / Prop firm scam checklist
Sources: Moneta Funded official site (Challenge Builder on the home page, checkout); official help articles "1-Step Challenge," "2-Step Challenge," "Instant Funding Account," "Trailing Drawdown," "Max Floating Loss," "Consistency Rule," "Daily Permitted Loss," "Product Offerings," "Payout Methods," "Refund Policy" (checked September 27, 2026); Moneta Funded help center and support's written answer (October 12, 2026); Trustpilot: Moneta Funded; Natsuki Nuts' note post "MONETA FUNDED: all 6 plans explained" (September 8, 2026); Natsuki Nuts on X: appointment as Japan business developer; Natsuki Nuts on X: firm's answer that martingale is banned on all plans and averaging down is conditionally allowed (September 9, 2026); Finance Magnates: Moneta Funded launch (January 2026); FXStreet: Instant Funding Pro announcement (May 2026); Blueberry Funded checkout and help center (checked September 10, 2026).
Written by
Hosono P | the prop firm strategist
I buy challenges with my own money and record everything through to the payout. Recorded payouts: ¥6.1M in total from Fintokei, Fundora and Funded7, plus $14,297 from The5ers and RZR Funded (as of November 2026). Author of the semi-discretionary EA "ELDRA".